Breaking
Latest tech news from South Africa and around the world•Stay updated with breaking technology developments•Innovation and digital transformation news•AI, gaming, and gadget updates daily•Crypto and fintech news from Africa•
 SA Tech News Desk
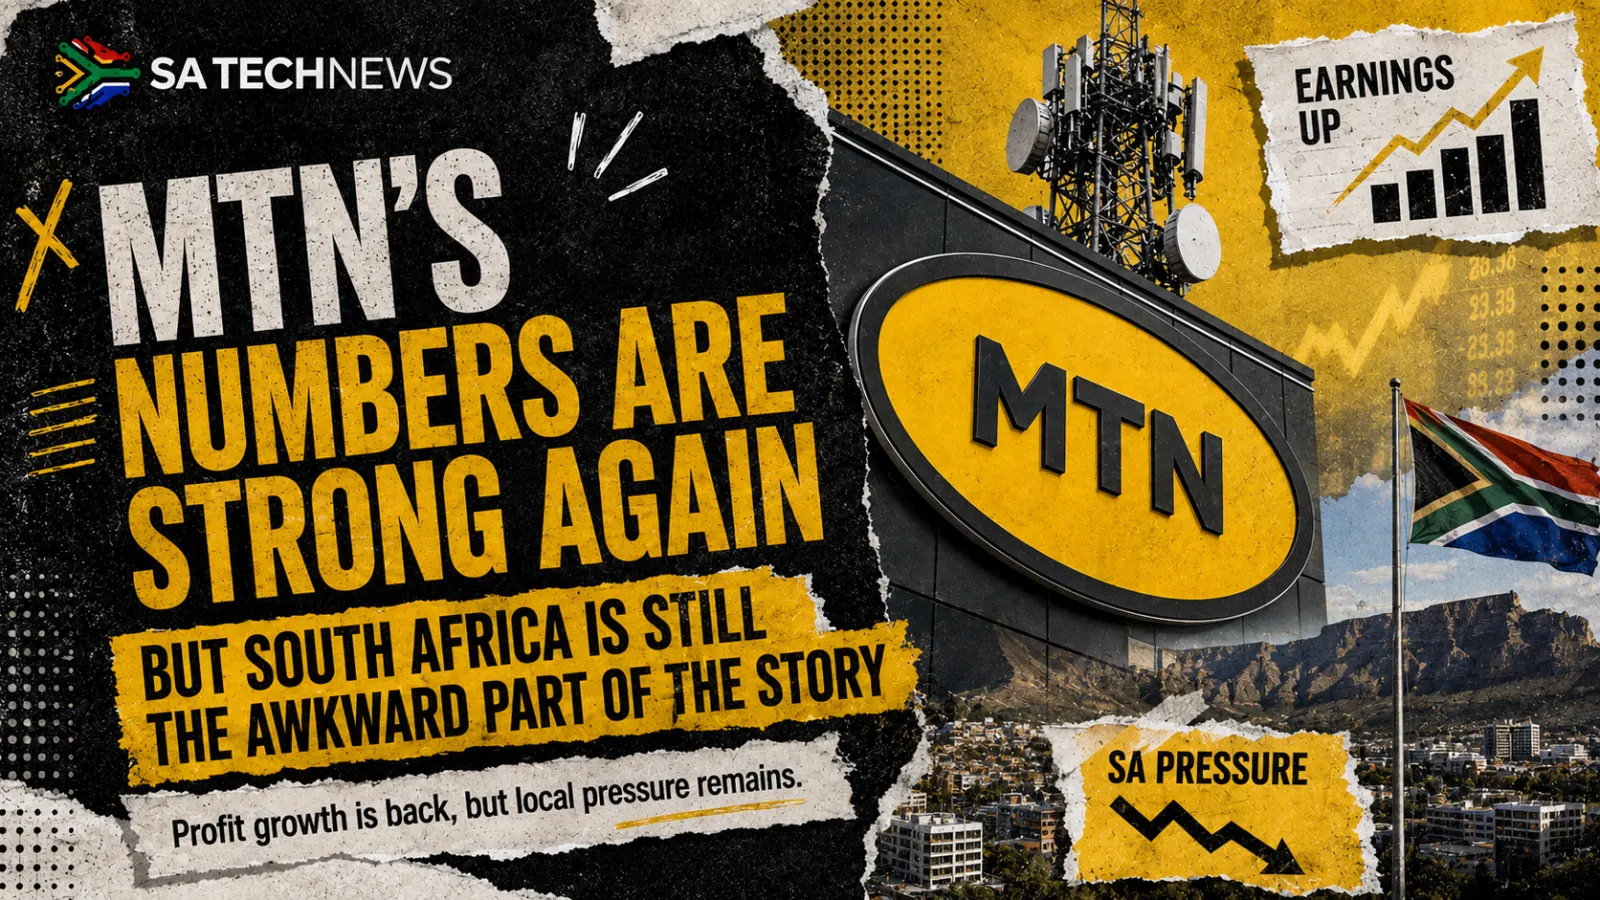
MTN's adjusted half-year profit rose more than 21% on subscriber growth across Africa. Investors will still watch South Africa hardest.
MTN has delivered the kind of half-year numbers that make a results presentation easy to open with.
Adjusted headline earnings per share rose 21.3% to 793 cents for the six months ended June, up from 654 cents a year earlier. Group service revenue, excluding currency effects, climbed 17.5% to R115.3 billion. Core earnings rose 24.4% to R56 billion and the EBITDA margin widened by 3.1 percentage points to 47.1%.
Those are not marginal improvements. They are the numbers of a group that is extracting real operating leverage from a network footprint that now stretches across 19 markets and serves more than 317 million customers.
But there is an awkward split inside the result.
The further MTN gets from South Africa, the better some of its growth numbers look.
Nigeria grew service revenue 25.7%. Ghana was up 32.3%. Cameroon, Uganda and Côte d'Ivoire also contributed strongly. South Africa, by contrast, managed service revenue growth of just 1.5%, with pressure in prepaid still weighing on the local business.
That does not make MTN South Africa a weak asset. It does show just how different the group has become from the mobile operator many South Africans still think they know.
MTN's strategy over the past few years has been built around scale: more data users, more fintech activity, more enterprise services and more customers across markets where smartphone adoption and data consumption still have room to grow.
The latest results suggest that strategy is working.
In higher-growth markets, the combination of subscriber additions, increased data usage and higher-value digital services is producing the kind of double-digit growth that is increasingly difficult to find in a mature market such as South Africa.
That matters because the economics of telecoms are unforgiving. Networks demand constant capital expenditure whether subscriber growth is exciting or not. Spectrum must be bought. Towers need power. Fibre backhaul must be expanded. Customers want more data for less money every year.
The best way to absorb those costs is to put more traffic and more customers over the same infrastructure.
That is easier in markets where mobile penetration, smartphone adoption and formal financial access are still expanding quickly.
It is harder in South Africa, where nearly everyone who wants a SIM already has one, often more than one.
MTN South Africa still sits at the centre of the group's identity, technology capability and balance sheet. It is also one of the most sophisticated mobile markets in the group.
But sophisticated does not mean easy.
The local prepaid market is ferociously competitive. Vodacom, Telkom, Cell C and a growing collection of mobile virtual network operators are all fighting for customers who have become extremely price sensitive. Promotions are copied quickly. Data bundles are compared constantly. Customers switch networks with little sentimentality.
At the same time, the regulatory environment keeps pushing prices down and tightening consumer protections around data expiry, rollover and out-of-bundle billing.
That is good for users. It is less comfortable for operators trying to grow revenue faster than inflation.
MTN's 1.5% local service revenue growth therefore needs to be read in context. The South African business is no longer the obvious engine of group growth. It is increasingly the mature cash-generating platform sitting alongside faster-growing African operations.
That is not necessarily a problem. Plenty of multinational companies would happily own a mature home market while their expansion markets do the heavy lifting.
The risk is that local competition becomes so intense that South Africa shifts from "mature" to "structurally low-growth".
Reported headline earnings per share actually declined 5.8%.
The difference between adjusted and reported earnings came largely from items that MTN treats as non-operational or exceptional, including a non-cash impairment on its 49% stake in Irancell linked to the Iran conflict, and foreign-exchange losses in South Sudan.
That distinction matters.
MTN operates in markets that can deliver extraordinary growth, but those same markets expose the group to political instability, currency volatility and regulatory shocks that a purely South African operator would never face at the same scale.
The group's geographic diversity is therefore both its greatest advantage and one of its biggest risks.
Nigeria can add enormous revenue growth in one year and create painful currency translation problems in another. Ghana can deliver excellent margins while another market deals with conflict or exchange controls.
Investors are being paid for accepting that complexity.
Revenue growth gets the headlines, but the 47.1% EBITDA margin deserves attention.
A 3.1 percentage-point improvement at MTN's scale means the company is converting a larger share of every rand of service revenue into operating earnings before interest, tax, depreciation and amortisation.
That points to better cost discipline and stronger operating leverage, not simply more customers.
Telecom groups have spent years trying to simplify operations, share infrastructure, reduce tower costs, migrate customers onto digital channels and cut expensive legacy processes.
Those efforts are not glamorous. They are also where a large portion of the value is created.
MTN's challenge now is to keep expanding margins without starving its networks of investment. Mobile users notice quickly when cost cutting becomes network congestion, slower speeds or poor customer support.
MTN continues to position itself as more than a mobile network, with fintech one of the pillars of its long-term growth plan.
That story has been uneven over the years, particularly in South Africa, where banks already have strong digital products and consumers have no shortage of payment options.
Elsewhere in Africa, the opportunity is much larger.
Mobile money can sit at the centre of day-to-day economic activity in markets where traditional banking infrastructure is thinner. That gives MTN a second growth engine beyond selling airtime and data.
The interesting question is whether fintech eventually becomes material enough to change how investors value the group.
For now, telecom revenue remains the anchor.
MTN has done the first part well: stabilise the balance sheet, grow service revenue, lift margins and keep its large African operations moving.
The next stage is harder.
South Africa needs new growth areas because the basic mobile market is mature. Enterprise connectivity, fibre, digital services and financial products all matter, but none is guaranteed to grow fast enough to transform the local operation on its own.
Across the rest of the continent, MTN has to keep expanding without allowing currency and political risks to swallow the returns.
That is why the latest half-year result feels strong without feeling simple.
A 21.3% increase in adjusted profit is excellent. A 17.5% increase in constant-currency service revenue is even better. But the internal geography tells the real story.
MTN is increasingly an African growth company headquartered in South Africa, rather than a South African mobile network with a collection of foreign operations.
That distinction will matter more with every set of results.
Source: SA Tech News