Breaking
Latest tech news from South Africa and around the world•Stay updated with breaking technology developments•Innovation and digital transformation news•AI, gaming, and gadget updates daily•Crypto and fintech news from Africa•
 SA Tech News Desk
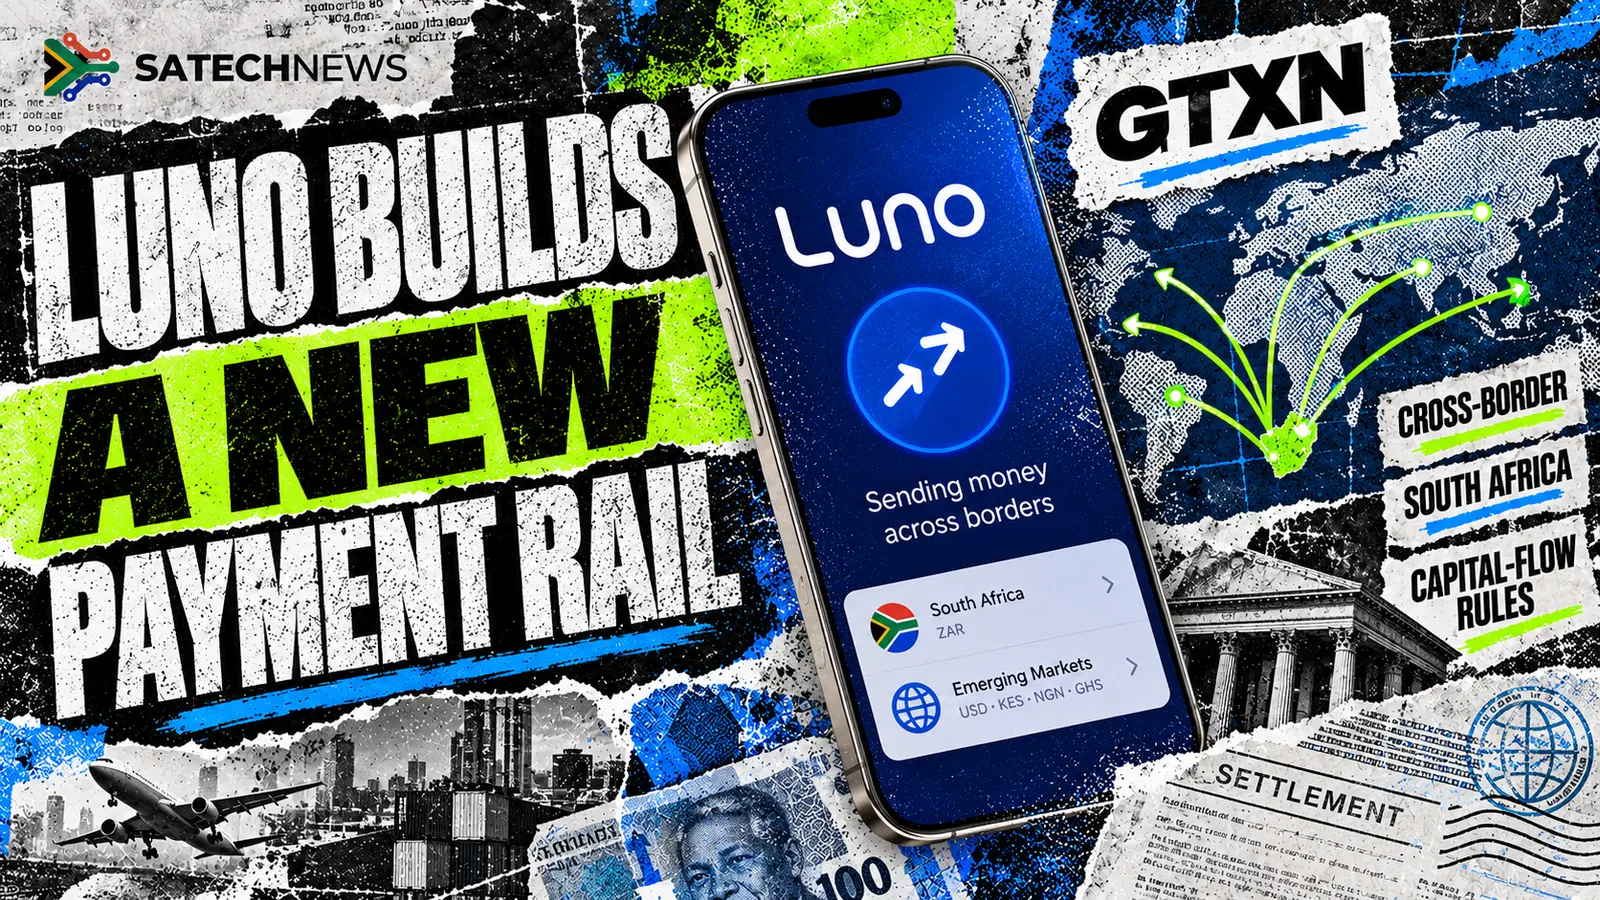
Luno has acquired GTXN to bring licensed cross-border payment rails into its group as South Africa rewrites rules for crypto-linked capital flows.
Luno has acquired GTXN, a licensed cross-border payments provider, as it tries to move beyond retail crypto trading and deeper into the business of moving money between developed and emerging markets.
The South African relevance is immediate. Cross-border payments remain slow and expensive for many businesses, while National Treasury and the South African Reserve Bank are still refining how crypto-linked flows should fit into the country's capital-control framework.
Luno says GTXN gives clients a single route for collection and payout, using infrastructure inside the wider group rather than a chain of correspondent banks.
Traditional cross-border transfers often pass through several intermediary banks. Each one can add a settlement delay, compliance check, currency conversion and fee. The problem can be worse in emerging markets where direct banking relationships are thinner. A payment may move through multiple institutions before reaching the final recipient.
Luno's argument is that owning more of the payment rail can reduce those hops. GTXN brings licensed collection and payout infrastructure into the group, while settlement can draw on Luno's liquidity.
That does not make regulation disappear. It makes the compliance model more central to the product. A cheaper corridor that cannot explain source of funds, sanctions screening and SARB reporting is not a product South African compliance teams will touch.
Importers, exporters, marketplaces and groups paying contractors across Africa already know the pain: two-to-five day settlement, opaque FX, and a bank that wants another form. Fintechs have chipped at that for years. Few have done it at scale without becoming, in practice, a bank plus a spreadsheet.
Treasury and the Reserve Bank are consulting on a new Capital Flow Management Regulations framework and a Draft Crypto Asset Manual for Cross-Border Activities. Those documents will shape how digital assets are treated when value moves into or out of South Africa.
Luno has argued that legitimate business payments using stablecoins or other regulated digital-asset infrastructure should not be treated as suspicious simply because the settlement technology differs from a conventional bank transfer. GTXN now sits directly inside that debate.
If the final rules allow licensed providers to move value efficiently while preserving reporting and compliance obligations, businesses could get more competition in a market long dominated by banks and specialist forex providers. If the rules are too restrictive, the acquisition may have less impact locally than Luno hopes.
FSCA licensing of crypto-asset service providers is the consumer-facing half of the story. Capital-flow rules are the corporate-treasury half. Luno needs both if GTXN is going to be more than a foreign corridor with a Cape Town press release.
GTXN is led by Dan Kleinbaum, who previously co-founded Beyonic, a mobile-money platform that operated across seven African markets before being acquired by Onafriq in 2020. That background matters because the proposition is less about speculative trading than about treasury, settlement and payment infrastructure.
Luno says GTXN now operates as its cross-border payments capability across its markets. For businesses, the claimed benefits are fewer intermediaries, clearer pricing and quicker settlement. Those claims still need to be judged against real corridor pricing, settlement times and banking alternatives.
South African groups with subsidiaries in Kenya, Nigeria or the UK will ask the boring questions: which currencies, which cut-off times, who the local payout partner is, what happens on a public holiday, and whether invoices can be reconciled without a crypto operations hire. If the answer requires explaining blockchain to a finance director who only wanted to pay a supplier, the product is not finished.
Retail Luno customers should not confuse this with cheaper Bitcoin withdrawals. GTXN is a B2B rail. The strategic point is that Luno wants to be infrastructure, not only an app that sells coins.
South African banks remain deeply embedded in settlement, compliance and corporate treasury. They also own the customer relationships GTXN wants. Partnership is more likely than replacement, at least at first: a bank that wants a faster corridor may white-label; a bank that sees leakage will slow onboarding.
Competition Commission and National Payment System considerations sit in the background whenever a non-bank tries to become ordinary financial plumbing. Luno has regulatory approvals across core markets, but cross-border payments are governed by more than one licence or one jurisdiction.
The final South African capital-flow rules are still being shaped. A cheaper rail is only useful if businesses can trust it at scale, with documented uptime, dispute processes and audit trails.
The acquisition therefore matters less as a crypto-market story than as a test of whether a crypto-native company can become ordinary financial infrastructure. South African businesses should watch the final Treasury and Reserve Bank rules closely. They will determine how much of GTXN's promise can be used locally rather than merely marketed from here.
The GTXN deal works if a South African finance team can pay a Nairobi or London counterparty faster and cheaper than the bank quote, with a file their auditor understands.
It fails if capital-flow rules stall the crypto-linked bits or if payout partners flake on a Friday. Watch the final Treasury and SARB manuals, then watch one live corridor's SLA. Retail Bitcoin volumes are a different business. This one will be judged in basis points and days, not in token price.
Source: SA Tech News


