Breaking
Latest tech news from South Africa and around the world•Stay updated with breaking technology developments•Innovation and digital transformation news•AI, gaming, and gadget updates daily•Crypto and fintech news from Africa•
 SA Tech News Desk
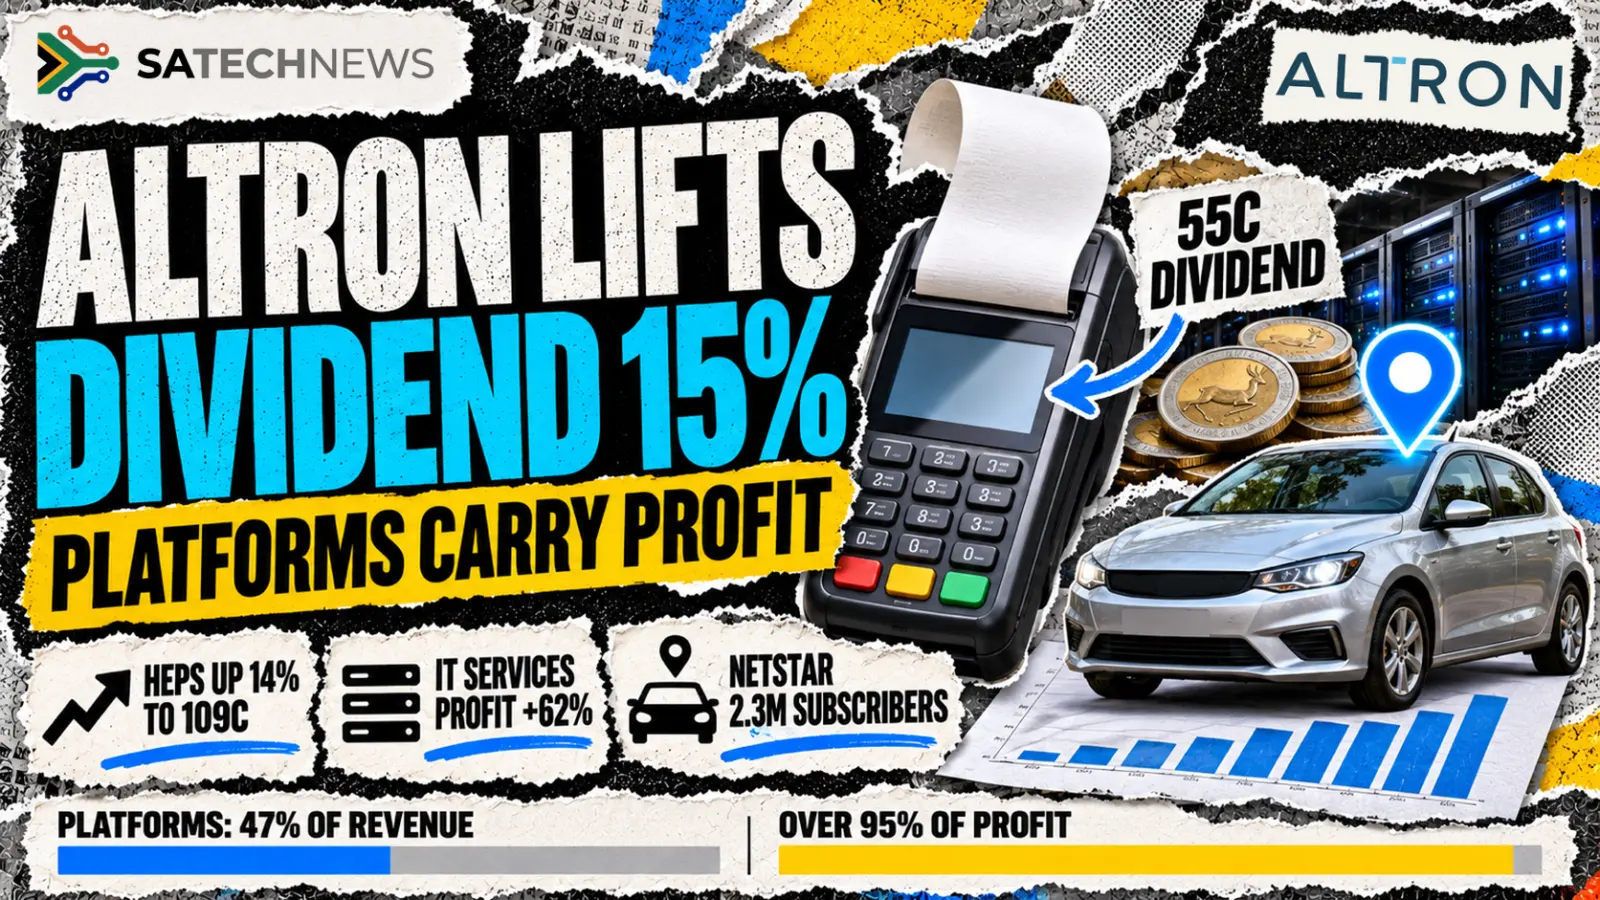
Altron's interim dividend rose 15% to 55c as HEPS climbed 14%. Platforms made over 95% of profit, and IT services gains leaned on hardware sales.
Altron has raised its interim dividend by 15% to 55c a share after a half-year in which its long-struggling IT services businesses made more money and its platform units kept carrying the group.
Headline earnings per share from continuing operations rose 14% to 109c for the six months to August, inside the 107c to 112c range the JSE-listed group flagged in its September trading statement. Revenue rose 5% to R5.1bn, which chief executive Werner Kapp called the group's strongest interim top-line growth in three years. EBITDA rose 16% to R1.09bn and net profit 17% to R385m, TechCentral reported.
For South African investors the useful number is the split. Netstar, Altron FinTech and Altron HealthTech produced 47% of revenue and more than 95% of operating profit. In profit terms Altron is now a payments, vehicle-tracking and health-data business with an IT services arm attached.
That split is the story of the half, more than the 15% dividend. Just under half of the revenue, 47%, produced more than 95% of the operating profit. The rest of the group, the IT services side, can improve sharply and still not be where the profit sits. The dividend of 55c, the 109c of headline earnings, the R5.1bn of revenue, the R1.09bn of EBITDA and the R385m of net profit are the group totals around that split. The 109c landed inside the 107c to 112c band from the September trading statement, so the earnings line did what the group had already told the market to expect.
IT services revenue rose 4% to R2.5bn and operating profit jumped 62% to R99m. The biggest swing came at Altron Digital Business, which made an operating profit of R22m against a R42m loss a year earlier on revenue up 8% to R1.6bn.
The detail is less tidy. Hardware and goods revenue in that unit rose 42% to R502m, while maintenance, support and outsourcing fell 10% to R505m. Hardware sales tend to be lumpy and thin-margin, and the recurring services revenue that makes an IT services business valuable went backwards. Management pointed to better order intake and contract renewals, which would need to show up in the next set of numbers.
Put those two lines next to each other. Hardware and goods at R502m, up 42%. Maintenance, support and outsourcing at R505m, down 10%. They are almost the same size this half. A year ago the services line was the larger one. The profit recovery at Digital Business, from a R42m loss to a R22m profit, arrived in a half when the lumpier line grew and the recurring line shrank. Order intake and renewals are what management pointed to. They are not yet the next set of numbers.
Altron Security went the other way. Revenue fell 18% to R207m and operating profit dropped to R29m from R70m. The group blamed the timing of software revenue in its identity and digital signing business and weak enterprise spending in a smaller IT services component, where it has started what it called corrective action. The unit did finish rolling out Zambia's national public key infrastructure.
Altron Document Solutions grew operating profit 45% to R48m, and distributor Altron Arrow lifted revenue 35% to R388m.
Altron FinTech is now the largest profit contributor. Revenue rose 14% to R858m and operating profit 17% to R300m. Debit orders processed grew 14% by number and value, and rented point-of-sale devices rose 61% to more than 30,000.
Netstar grew subscribers 8% to 2.3 million with churn steady at about 16%. Revenue rose 6% to R1.3bn as annuity income climbed 11% to R1.2bn, offset by a 43% drop in hardware sales to R71m. Its revenue outside Africa, mainly Australia, fell 22% to R156m. Altron says the Australian operation has stabilised and is profitable.
Altron HealthTech grew revenue 2% to R205m and EBITDA 13% to R76m.
Cash generated from operations rose 32% to just over R1bn. Capital expenditure rose 21% to R447m, mostly on rental devices for Netstar and point-of-sale terminals for FinTech. The group still had more than R800m in net cash after paying R755m to shareholders in June, which covered the final and special dividends for the 2026 financial year.
FinTech's R300m of operating profit is the single largest contribution, on R858m of revenue. Netstar's revenue is larger, at R1.3bn, and most of that is annuity: R1.2bn, up 11%, against hardware of R71m, down 43%. Subscribers are 2.3 million, up 8%, with churn still about 16%. HealthTech is the small one of the three: R205m of revenue, up 2%, and R76m of EBITDA, up 13%. The cash line is separate from those trading figures. Operations produced just over R1bn, up 32%. Capex of R447m, up 21%, went mostly into the devices Netstar rents and the terminals FinTech places. After the June payout of R755m, net cash was still above R800m.
Altron calls this financial year "a deliberate reset and investment year" for Netstar, without saying what the reset costs or when it ends. Netstar also said in June that it plans to sell anonymised vehicle movement data, and the results give no revenue figure for that yet. In IT services, the open question is whether the profit recovery lasts once the hardware boost fades, given that maintenance and outsourcing revenue fell 10% in the half.
The dividend can rise 15% while those questions stay open. A reset without a cost or an end date, a data product with no revenue line yet, and a services profit that leaned on hardware are the three items the next results would have to answer. This half answers the trading statement: 109c, inside 107c to 112c, and 55c a share.
Source: SA Tech News